Indicators
VWAP in MT5: session anchors, volume sources and reset rules
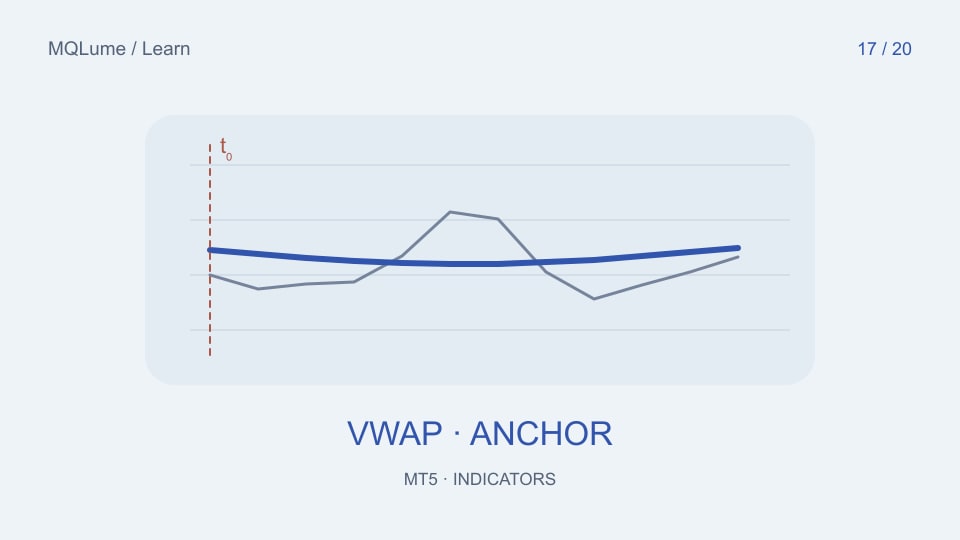
VWAP needs a price, a weight and an anchor
A volume-weighted average price is the sum of price×volume divided by the sum of volume over a defined interval. A useful implementation must specify which price observations it uses, what “volume” means and where the accumulation starts.
VWAP is not part of the standard built-in indicator list documented for MT5. Custom implementations are available, and they can differ materially. Do not assume that two indicators with the same name use the same session or weighting.
Calculate a small weighted average
With synthetic prices [100,102,101] and weights [10,20,30], the weighted numerator is 1000+2040+3030=6070 and the total weight is 60. VWAP is approximately 101.1667. The ordinary mean is 101, so unequal weights change the result.
If the weights are tick counts and the price is each bar's typical price, describe the result as a tick-volume-weighted bar-price approximation. It is not identical to an exchange calculation from every executed trade.
Make reset rules explicit
A daily reset based on broker midnight can differ from an exchange-session reset or a user-selected anchor. Record the timezone, daylight-saving policy and treatment of breaks. A chart timezone label alone does not guarantee that the indicator uses the same session boundary.
At a new anchor, reset both numerator and denominator. With zero accumulated weight, expose a missing value rather than dividing by zero or carrying the previous session's value without explanation.
Do not add the current bar repeatedly
On every tick, the current bar's price and volume can change. Adding its full cumulative contribution again on each call double-counts it. A simple design stores the completed-bar totals and recomputes the current bar's contribution from its latest values.
When history changes or the anchor moves, rebuild from the defined start. An incremental implementation should match a full pass over the same fixture. Test a session boundary, zero volume and an updated current bar explicitly.
Treat distance from VWAP as a description
Price above VWAP means price is above the selected weighted average under those assumptions. It does not prove that a reversal or continuation is imminent. A different anchor can change that relationship without any new market event.
Before comparing tools, verify their anchor and data contract using the volume-source guide. Then validate the numerical series before adding any trading rule.